What Does 62 Cost Someone Born in Your Year?
Pick your birth year. These are Social Security's own rules, worked out for you.
At 62 your check is 30% smaller. At 70 it is 24% larger. Both last for life.
Claiming at 62 isn't wrong. Choosing it by accident is.
Your five dates, for someone born in 1965.
See every birth year, 1943 to 1960 and later ▾
| Born | Full retirement age | At 62 you get | At 70 you get |
|---|
You can't change your birth year. You can choose your month, your Medicare window and your withdrawal order on purpose, before any of them choose for you.
Source: Social Security Administration, "Benefit reduction for early retirement" and "Delayed retirement credits" (ssa.gov/oact): 5/9 of 1% for each of the first 36 months before full retirement age, 5/12 of 1% for each month beyond that, and 2/3 of 1% for each month you wait past it, up to 70. Medicare: medicare.gov. RMD ages: IRS. Dollar figures use the amount you enter and leave out yearly cost-of-living raises. Nothing you type leaves your browser.
The Offer
Three books, four bonuses, one honest price.
Launch price — ends with the timer
Only want one book? Book 1 · $19 · Book 2 · $19 · Book 3 · $19
Single books are the book only. The four bonuses come with the set.
Two Ways to Pick Your Dates
What a guess can cost, and what checking first costs instead.
If you guess
| Claim at 62 instead of 67Linda's check: $1,900 becomes $1,330 | $570 less a month, for life |
| Sign up for Part B two years late$40.58 more a month at 2026 rates | +20% on every premium |
| Take $12,000 from an IRA at 58, no exception | $1,200 extra tax |
| Miss a $10,000 required withdrawal10% if you fix it in time | $2,500 excise tax |
| The claiming gap alone | $6,840 a year |
If you check first
| Your Social Security statement at ssa.gov | Free |
| Your 7-month Medicare window on a calendar | Free |
| A 15-minute call to HR with the 8 questions in Book 1 | Free |
| The three books, the workbook and the phone scripts | $37 |
| One time | $37 |
Claiming early isn't always wrong. Book 2 lists 8 situations where it makes sense. The cost comes from picking the date by accident.
Early-claiming reduction: SSA. Part B late penalty: medicare.gov; 2026 standard Part B premium $202.90 a month (CMS). 10% additional tax on early withdrawals and the 25% / 10% excise tax on missed RMDs: IRS.
Linda is a composite teaching example used throughout the books, not a real person; your numbers will differ. Rules and amounts are for 2026 and can change. Educational content, not personal financial, tax or legal advice.
What's Inside
Three books, 500+ pages, one plan — in the order you'll need it.
The 5-Year Retirement Checklist
Everything to do while you're still getting a paycheck.
- A one-page worksheet for how much you really need
- Three official places to find an old 401(k), and what to say when you call
- The 2026 catch-up limits, including $11,250 at ages 60 to 63
- Pay off the mortgage or keep investing: a side-by-side test
- Your last 90 days at work, dated, and the 8 questions to ask HR
Before You Claim Social Security
The decisions you make once and live with for decades.
- Read your statement line by line, and fix an earnings error
- 62, 67 or 70: your three numbers and the age they come out even
- 8 situations where claiming early makes sense
- Spouse, ex-spouse and survivor rules in plain words
- Medicare dates, the late penalties, and Medigap vs. Medicare Advantage
How Not to Run Out of Money in Retirement
Turn a balance into a paycheck that lasts.
- The paycheck method: savings into a monthly amount
- The 4% rule: where it works and where it breaks
- Which account to take money from first
- How Social Security is taxed, RMDs, and the April 1 trap
- Roth conversions: 6 signs it pays and 6 signs it doesn't
Plus the Key Dates Card, the Workbook, the Phone Scripts Pack, and large-print editions of all three.
Where Every Number Comes From
Every rule in these books is checked against the agency that sets it.
Each chapter ends with its sources. The 2026 edition uses the figures published for 2026.
A Note from the Author
Why these books exist, and how they're put together.
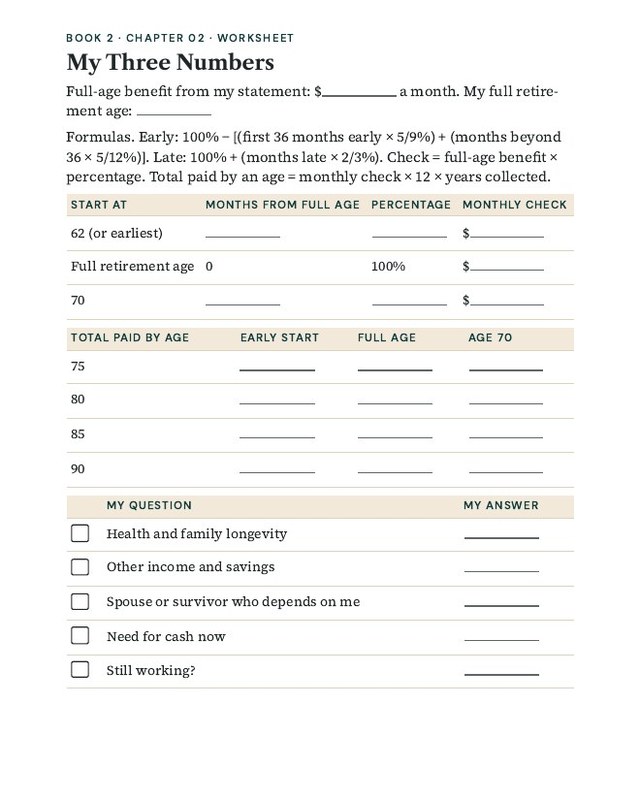
Most retirement advice tells you what to think about. These books tell you what to do, and by when: which form, which phone number, which month, and what to say when someone picks up.
Every chapter follows one ordinary example through the rules, with the 2026 numbers checked against the agency that sets them. Every chapter answers one question: what exactly do I do, and by when?
Read them for a week. If they don't earn their keep, get every cent back.
Open your Social Security statement and fill in Book 2's three numbers. Put your Medicare window on the calendar. Look up one old account. If after 7 days you don't feel clearer about your dates, ask for a refund through Hotmart or by email and you'll get every cent back, no questions asked.
Get the Set — $37Order the Retirement Money Guides
$37 once. No subscription. Yours to keep.
Launch price — ends with the timer
Questions Buyers Ask First
Is this another "always wait until 70" pitch?
No. Book 2 shows what each age pays and lists 8 situations where claiming early makes sense. It never tells you which age to pick. The point is that you pick it on purpose, with your own numbers in front of you.
I don't have a lot saved. Is this for me?
The main example, Linda, has $180,000 saved and a $1,900 Social Security estimate. Most of the books are about dates and rules, and those matter more when there's less room for a mistake.
I already have a financial advisor.
Good. These books help you ask better questions and check what you're told. Every chapter ends with "If you want help": who to call, and what to ask them.
I'm already retired. Is it still useful?
Book 3 is written for you: withdrawals, taxes, RMDs, your house and your family paperwork. Book 2 still helps if you haven't claimed Social Security yet or are choosing Medicare coverage.
Can I buy just one book?
Yes, $19 each. The set costs less than the three bought one by one, and the four bonuses come only with the set.
Are the numbers current?
This is the 2026 edition. Every limit, premium and age is checked against Social Security, Medicare, CMS and IRS figures for 2026, and each chapter lists its sources.
How do I get it?
Right after checkout, Hotmart emails you the download links. They're PDFs: they open on any phone, tablet or computer, and the worksheets print fine at home.
What if it isn't right for me?
Then it costs you nothing. You have 7 days to ask for a full refund through Hotmart or by email, no questions asked.
Pick Every Date on Purpose
At 62 your check is 30% smaller, for life. At 65 the Medicare clock starts. At 73 or 75 the IRS wants its first withdrawal. Know your dates before they arrive. $37 once, instant download, 7-day money back.